1. The low-lying streets that flood every heavy rain
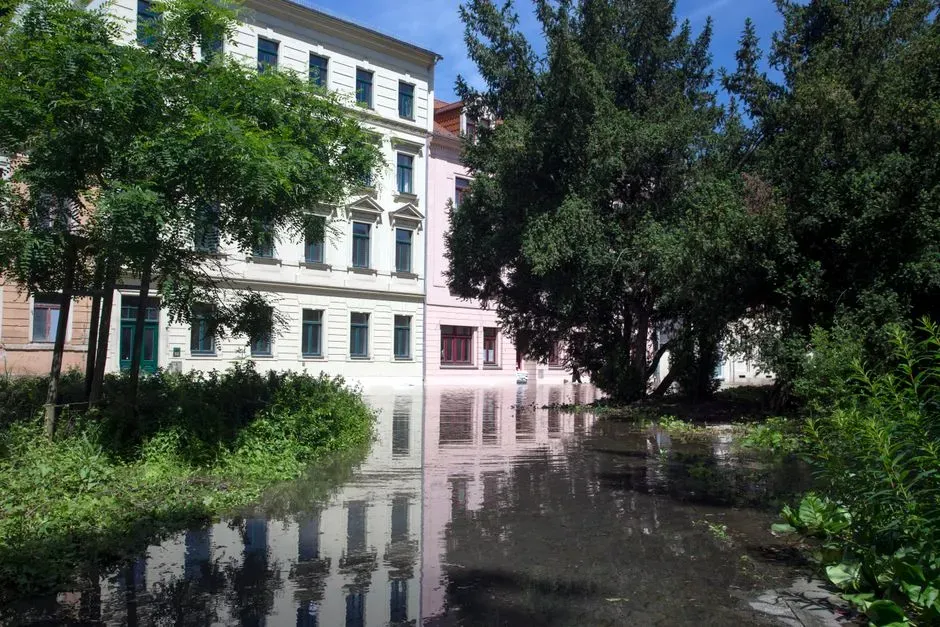
Every region has at least one neighborhood built on land that used to be a floodplain, a creek bed, or low-elevation ground that drains slowly. Locals know which streets pool water after a storm because they have watched it happen for years, even if the house itself never technically flooded. Nationally, this is a much bigger problem than most buyers assume. Nearly every county in the United States has experienced flooding in the past few decades, but just 4% of homeowners nationwide have flood insurance, according to the Federal Emergency Management Agency.
Part of the issue is that flood maps often lag behind reality. FEMA’s flood zone designations no longer reflect where modeled losses occur, and in 20 states, more than 70% of expected annual flood losses fall outside FEMA’s designated Special Flood Hazard Areas. A realtor showing a home outside an official flood zone is not being deceptive when they skip the topic, but a neighbor who has bailed out a garage twice will usually say something.
2. Wildfire-adjacent developments tucked against dry hillsides
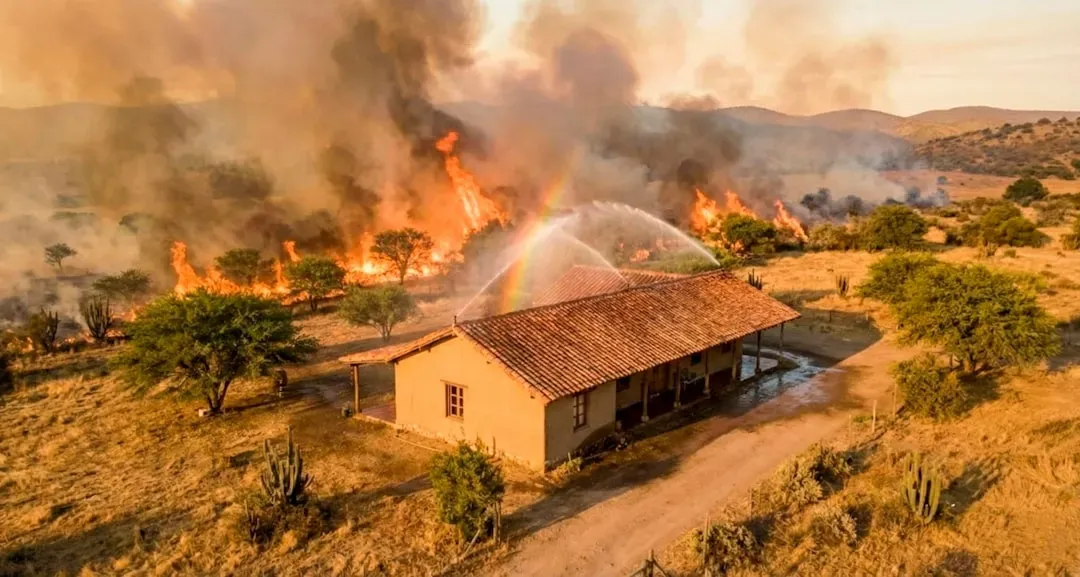
Homes built at the edge of dry brush or forest often look idyllic in photos, with mountain views and privacy that suburban buyers pay a premium for. Locals in fire country tend to know which canyons and ridgelines have burned before and which ones are simply overdue. The scale of this risk has grown sharply in recent years, and it is not limited to California anymore.
In 2025 alone, 77,850 wildfires burned more than five million acres in the U.S., according to the National Interagency Fire Center. The January 2025 fires around Los Angeles were a stark example of what locals had already suspected about certain zip codes. A deeper analysis of insurance trends in California’s Pacific Palisades and Altadena zip codes found these areas already were experiencing higher than average insurance rate increases and non-renewal rates before being struck by the Palisades and Eaton fires in 2025. That is exactly the kind of pattern a longtime resident notices long before it shows up in a listing description.
3. Neighborhoods where flood insurance premiums are quietly climbing
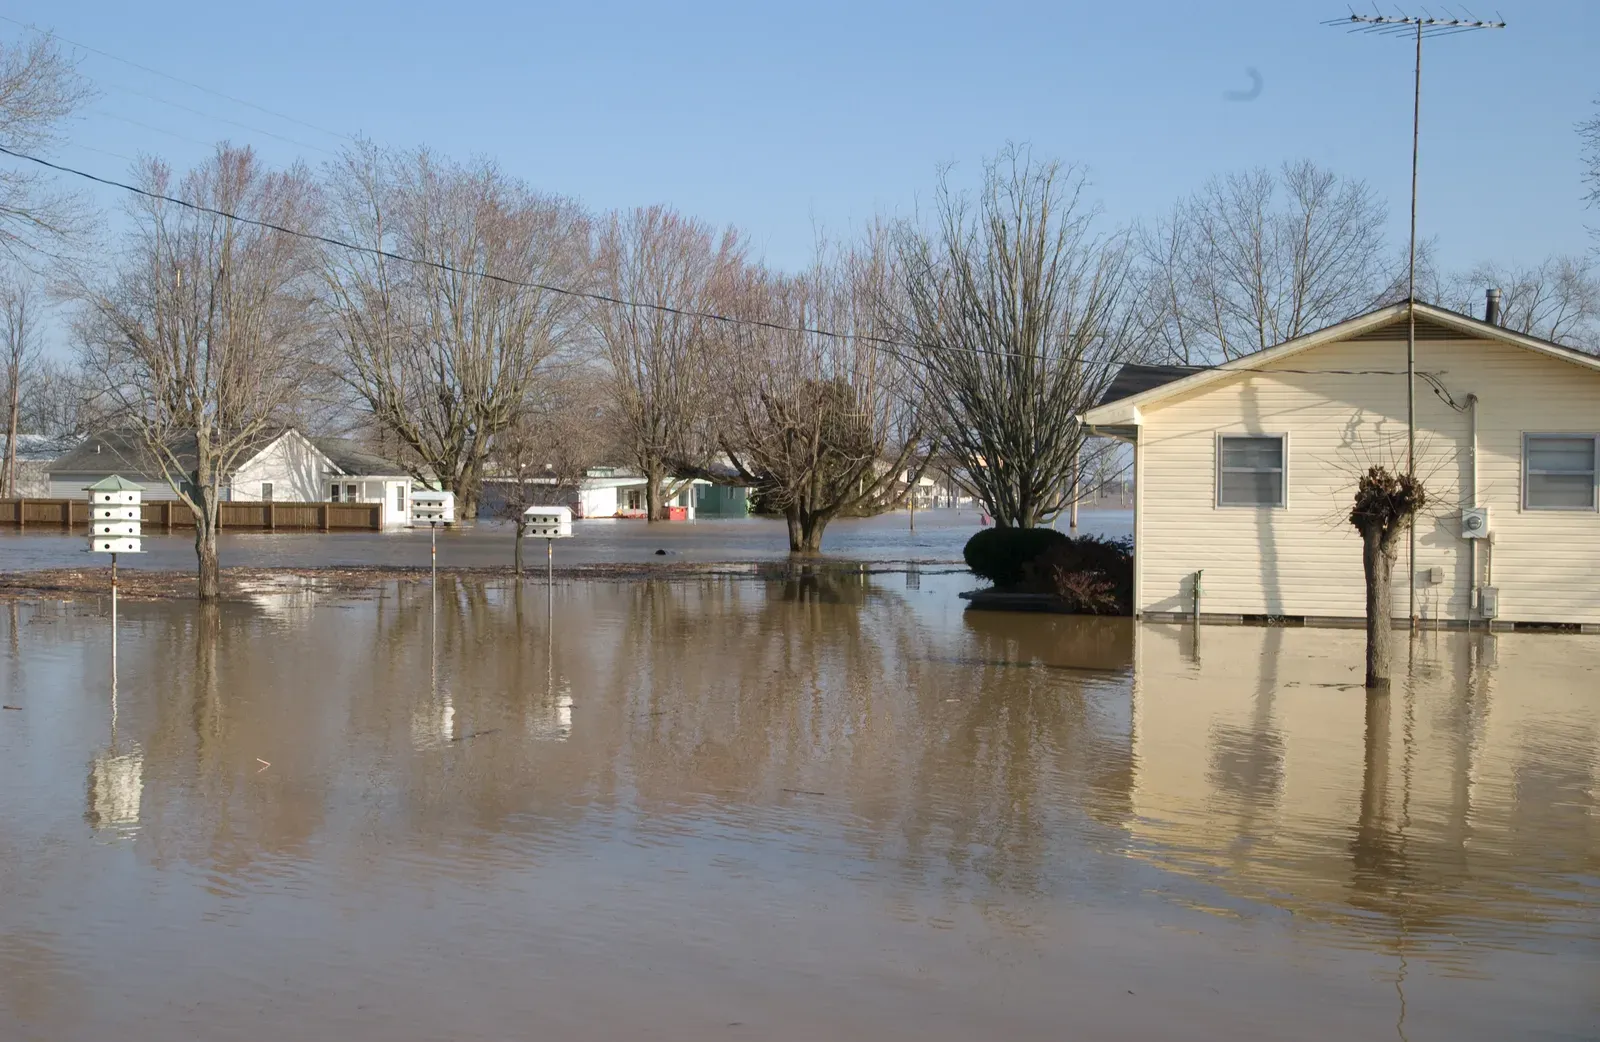
Some neighborhoods have not flooded catastrophically, but the cost of insuring a home there has been rising for years in a way that only becomes obvious once you own the place. Locals in these areas often mention, almost as an aside, that their premiums have doubled since they bought. This is not paranoia. From 2009 to 2023, the mean annual cost of a flood insurance policy for a single-family home increased by 82 percent, an average annual growth rate of approximately 4.4 percent, while flood insurance coverage has fallen.
Lenders are starting to catch up with what locals already sense. In June 2024, Freddie Mac released rules, effective April 2025, that require mortgage issuers to use full flood risk premiums in calculating housing expense-to-income and debt payment-to-income ratios for homes within Special Flood Hazard Areas. A realtor selling a home in one of these areas is generally focused on the sale price, not on projecting what your insurance bill will look like in five years.
4. Coastal subdivisions with rising storm surge exposure
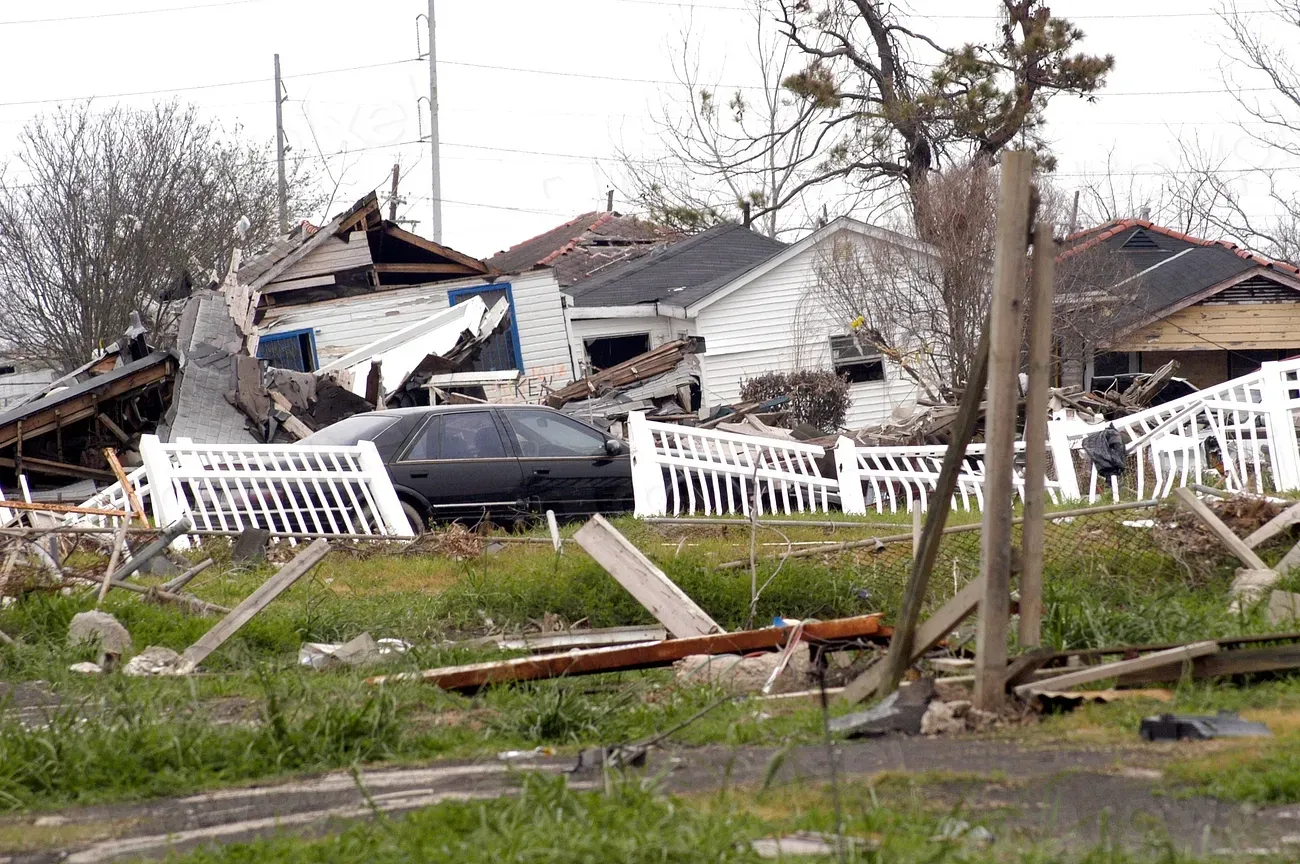
Waterfront and near-waterfront neighborhoods sell themselves. The view, the breeze, the sense of getting away from the everyday grind, all of that is real. What is harder to see on a tour is how much of the surrounding land is now considered exposed to storm surge, a risk that has expanded well beyond the immediate coastline in the last several years.
More than 6.4 million U.S. residential properties face storm surge risk in 2025, with a reconstruction cost value of about $2.2 trillion. States that draw the most relocation interest tend to carry the most exposure too. States like Florida, Texas, and Louisiana continue to see large exposure with storm surge risks driven by rising sea levels and stronger wind threats. Locals who have lived through a few hurricane seasons know which subdivisions get evacuation orders first and which ones quietly stay dry, information that rarely makes it into a property description.
5. Inland neighborhoods that feel safe but carry hidden flood risk
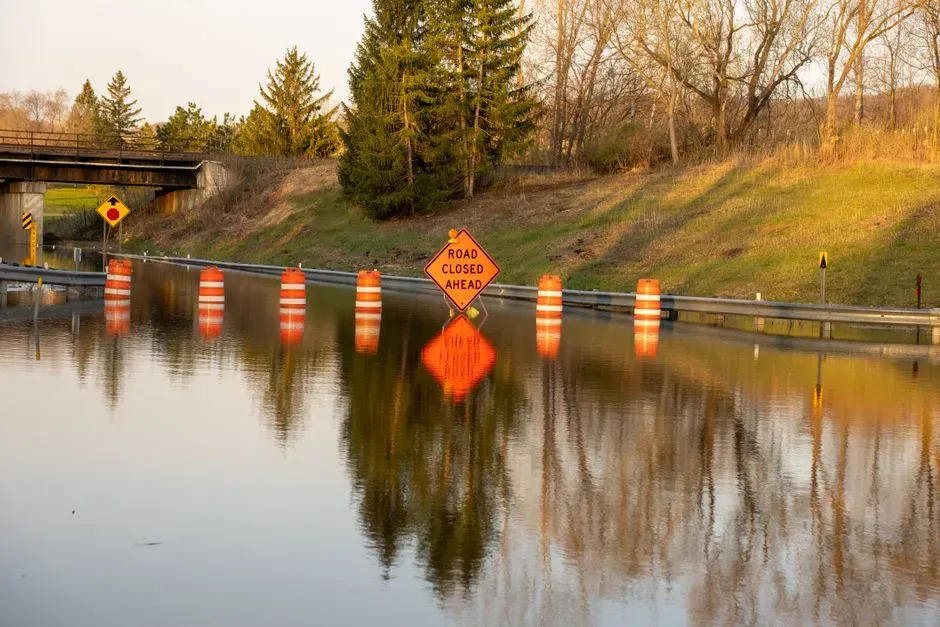
This is the category that catches newcomers most off guard, because it defies the obvious logic of avoiding the coast. Plenty of inland towns, nowhere near an ocean or a major river, have quietly become some of the least insured against flood risk in the country, even though the danger is rising fastest there. The coverage shortfall is an inland problem, not a coastal one, and eight of the 10 states with the greatest coverage deficits are inland states, where flood risk is growing fastest and FEMA flood maps are most outdated.
Some of the outdated mapping is almost startling once you see the numbers. In Nevada, 99.5% of FEMA flood maps are more than 10 years old, in New Hampshire that figure is 97.2%, and in Arizona it is 94.3%. A local who watched a flash flood tear through a neighborhood that had never flooded before will warn a newcomer instinctively. A listing agent working off official flood maps has no reason to bring it up at all, because on paper, the risk simply is not there.
6. Areas where insurers are quietly pulling back coverage
The clearest signal that a neighborhood has a reputation problem is not always visible on the ground. It shows up in whether insurance companies still want to write policies there at all. In several high-risk states, insurers have been retreating from entire zip codes, leaving homeowners to rely on state-backed plans of last resort that were never designed to carry this much of the market.
California’s FAIR plan grew from insuring 210,000 homes in 2020 to over 463,000 in 2024, with total exposure exceeding $450 billion. That kind of shift tends to be common knowledge among longtime residents long before it becomes obvious to someone moving in from out of state. Nationally, average premiums rose 3% during 2019 to 2024 but rose 25% or more in southern coastal areas, and wind risk affected premiums more than wildfire risk in most regions. A realtor can technically disclose known material defects about a property, but a slow-moving market pullback across an entire neighborhood rarely fits into that conversation.
None of this means these neighborhoods are unlivable or that everyone in them regrets buying. Plenty of people weigh the risks, decide the tradeoffs are worth it, and build good lives in exactly the kind of place this article describes. The real lesson is simpler: a five minute conversation with someone who has lived on the block for years will often tell you more than the listing sheet ever will.
Leave a Reply