1. Paper statements
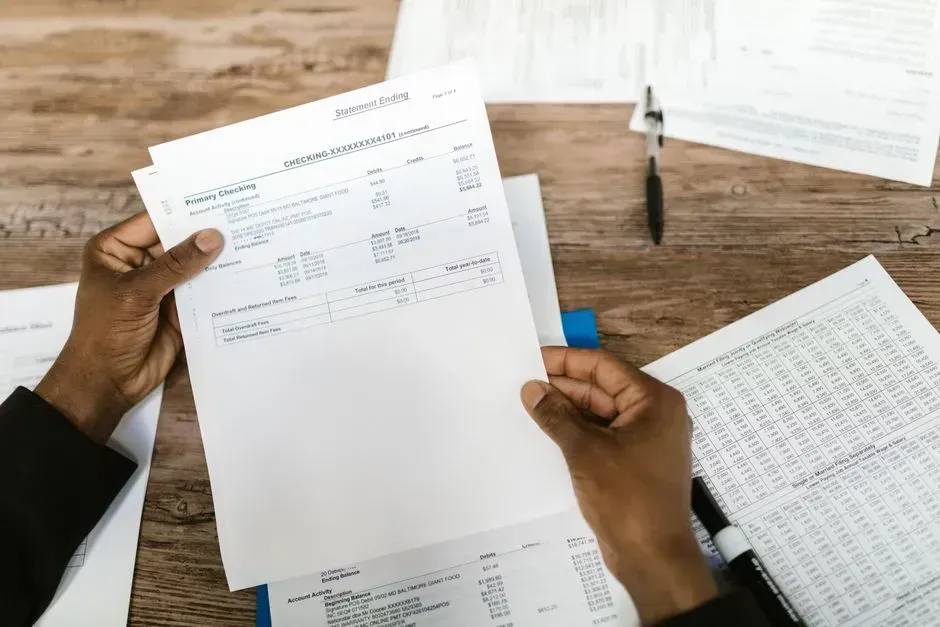
Getting a printed statement in the mail used to be the default, not a premium option. That’s no longer true at a growing number of institutions. If you don’t enroll in paperless banking, you may be charged $1 to $5 per statement to cover the cost of printing and mailing.
The rationale banks give is straightforward. Banks not only recoup some of their expenses related to printing and mailing, but they also incentivize clients to engage in more of their online banking services. The industry-wide numbers back up why this matters to them financially: the retail banking industry sent paper checking account statements to 69 million households at an average cost of $9 per customer. That cost gets passed along, and it disproportionately affects customers who never asked for a digital-first relationship with their bank in the first place.
2. Basic checking account maintenance
Monthly maintenance fees weren’t always applied to entry-level accounts. They used to be reserved mostly for premium tiers with extra perks. That’s changing fast, and the average cost has climbed to a new high. According to the MoneyRates survey, the average monthly maintenance fee has hit a record $13.51, or more than $162 a year.
Basic checking used to be the simplest product a bank offered, but the safety net is shrinking. Basic checking accounts were once the simplest and most affordable banking option, but now some banks are testing monthly maintenance fees even on entry-level accounts. The waiver conditions are also getting stricter, with minimum balance requirements increasing, and some banks requiring multiple qualifying transactions each month just to skip the charge.
3. Overdraft and non-sufficient funds coverage
For a stretch of time following regulatory crackdowns, overdraft fees looked like they might shrink permanently or disappear at some large banks. That trend has partially reversed. Banks have already seen increases in overdraft fee income after regulatory pressure eased, and many still charge around $30 per overdraft, with multiple charges stacking quickly if several transactions hit while an account is negative.
What used to feel like a rare, one-off inconvenience can now compound within a single day if several purchases post while a balance is briefly negative. Regulators haven’t ignored this. CFPB Circular 2024-05 targets violations by requiring no fee without proven consent and disclosures, and banks must send a model pre-opt-in form. Even so, the practical experience for many account holders is that a service which once felt like automatic courtesy now comes with a real price tag attached.
4. Out-of-network ATM withdrawals
Cash access used to feel like a basic utility, something a bank simply provided. Now it can trigger two separate charges in a single transaction. If you use an ATM from another company, you can be hit with two charges, one from your bank and another from the ATM operator.
These costs have crept upward over time rather than jumping all at once, which is part of why they’re easy to miss. ATM fees have been around forever and add up faster than expected, since using an out-of-network machine usually means paying twice, once to your bank and once to the ATM owner, together easily topping six dollars per transaction. A quick stop at the wrong machine can end up costing nearly as much as a small purchase, just to access your own money.
5. Wire and electronic transfers
Moving money used to be treated as a routine banking function, especially for domestic transfers. That convenience now carries a noticeable price, particularly when speed is involved. Moving money quickly often comes with a steep price, and wire transfer fees can exceed fifty dollars per transaction, especially for international transfers.
Domestic transfers aren’t exempt either, and the numbers vary widely by bank and destination. Domestic outgoing wires typically run $25 to $50, incoming wires around $15, while international SWIFT transfers can cost 3 to 8 percent in combined fees and currency exchange. For anyone who occasionally needs to send a large sum quickly, that markup can be a real surprise if they haven’t checked their bank’s fee schedule recently.
6. In-person and phone-based account support
Talking to an actual teller or getting help over the phone used to be baked into the basic banking relationship. Some institutions have started nudging customers toward automated channels instead, sometimes with a financial push rather than just a suggestion. Bank of America made this explicit years ago with an account structure that charged extra for using tellers, and the broader industry has continued moving in that direction since. Bank of America Corp offered an online bank account that charges a monthly fee for paper statements and using tellers, steering customers toward ATMs and online banking for basic services like deposits and withdrawals.
The logic hasn’t disappeared with time; if anything, it has spread. Newer account tiers at various banks now build in similar incentives, treating branch visits or live phone support as something to be discouraged rather than offered freely. For customers who prefer face-to-face banking or need extra help navigating an account issue, that shift can mean either paying more or adapting to a self-service model they didn’t necessarily choose.
7. Keeping a dormant account open
An account that sits untouched used to just sit there, no harm done. Increasingly, banks are attaching monthly charges to accounts that go quiet for too long. Dormant account fees typically apply after 12 to 24 months without activity, averaging $5 to $20 per month once triggered.
This fee often blindsides people who keep an old account open as a backup or for a specific, infrequent purpose, like receiving an occasional payment. Because the charge only kicks in after a defined stretch of inactivity, it’s easy to lose track of the clock until a statement shows a shrinking balance. A single missed transaction each year, something as simple as a small transfer or a debit swipe, is often enough to keep the fee from ever applying, which makes it one of the more avoidable charges on this list if customers know it exists.
Taken together, these seven changes reflect a broader pattern rather than isolated decisions by individual banks. Services that once came bundled into a standard checking relationship are increasingly treated as optional extras, priced individually and often activated by default unless a customer takes specific action to opt out. The fees themselves aren’t always large in isolation, but stacked across a year, they can quietly add up to a meaningful sum. Reading a fee schedule closely, and checking it again after any account update notice, remains the most reliable way to catch these charges before they become a habit.


Leave a Reply