Panama: the territorial tax classic
Panama has built its reputation on a simple idea: tax what happens inside the country, leave everything else alone. Panama’s territorial system does not tax foreign income when it is remitted or brought into Panama. That means Social Security checks, private pensions, and investment income from abroad arrive completely untouched by Panamanian tax authorities.
The country’s Pensionado visa makes qualifying refreshingly easy. Applicants must receive a minimum pension of USD 1,000 per month, or USD 750 if owning Panamanian real estate over USD 100,000. On top of the tax treatment, the visa offers discounts on entertainment, transportation, medical consultations, and restaurant bills. There is no minimum age requirement either, which surprises a lot of applicants who assume retirement visas are reserved for people already well into their sixties.
Greece: a flat rate with real staying power
Greece has quietly become one of Europe’s most compelling retirement tax stories. Greece taxes all foreign-sourced income, pensions included, at a flat 7% for up to 15 years for qualifying retirees who transfer their tax residence. That is a striking contrast to the alternative, since the single rate replaces a progressive scale that otherwise climbs to 44% on income above 60,000 euros.
Fifteen years is also unusually generous compared to similar programs elsewhere on the continent. Greece offers the longest runway and no town restriction, which gives retirees more freedom to choose where they actually want to live, whether that is Athens, an island, or a quieter mainland town. The trade-off is that the country still expects retirees to genuinely relocate their tax residence, not just visit a few weeks a year.
Italy: a striking rate with a location catch
Italy’s version of this idea is even lower on paper. Italy mirrors the idea with its own 7% flat tax on all foreign income for pensioners who relocate to qualifying small towns across eight southern regions, applied for 10 years. The catch has always been geography, since the benefit only applies in specific smaller municipalities rather than nationwide.
That restriction eased noticeably this year. Effective 7 April 2026, Italy raised the eligible municipality population ceiling from 20,000 to 30,000 and unlocked 74 new towns, with the biggest gains in Campania, Sicily, Puglia, and Sardinia. drawn to Italian food, history, and pace of life, this expansion opens up a much longer list of towns worth considering without giving up the tax advantage.
Cyprus: the best deal for pure pension income
Cyprus tends to fly under the radar next to Greece and Italy, but whose income is mostly pension based, it can actually beat both. Cyprus offers the lowest headline rate of all for pure pension income, plus a non-domicile status that exempts dividends and interest from the Special Defence Contribution for up to 17 years. That combination matters because it covers not just the pension check itself but the investment income that often sits alongside it.
The seventeen-year window is longer than what Greece or Italy offer, giving retirees a genuinely long horizon to plan around. English is widely spoken across the island, and the EU membership means healthcare and banking infrastructure feel familiar to many Western retirees. It is worth noting, though, that the benefit is structured around pension income specifically, so retirees with more varied income streams should run the numbers carefully before assuming Cyprus is automatically the cheapest option.
Malta: administration in English, at a price
Malta’s retirement programs come with a higher price tag but a smoother experience for English speakers. Expats can benefit from special tax regimes like the Global Residence Programme or the Malta Retirement Programme, which offer a flat 15% tax rate on foreign income, with a minimum tax of 15,000 euros per year. That minimum tax floor is the key detail, since it means the program favors retirees with higher pension income who can absorb that annual cost comfortably.
What Malta trades in flat-rate simplicity, it makes up for in convenience. Malta costs more in minimum tax but provides English-language administration and treaty relief. who want EU residency without wrestling with a foreign language for every tax filing or medical appointment, that convenience often justifies the extra cost.
Malaysia: territorial tax with a Southeast Asian twist
Malaysia’s Malaysia My Second Home program has gone through real turbulence in recent years, tightening requirements and shifting tiers, but the core tax appeal has held up . As an MM2H resident in Malaysia, all foreign-source income, including pension, interest, and dividend income, as well as foreign earned income, is exempt from Malaysian taxes. That is a meaningful benefit in a region where cost of living already runs low compared to Western Europe or North America.
The financial thresholds now vary by tier, which is important to understand before applying. For the Silver tier, applicants aged 50 and above must show a fixed deposit of RM 150,000, monthly offshore income of at least RM 5,000, and liquid assets totaling RM 150,000 or more. It is worth flagging that Malaysia’s broader tax rules for locally sourced or remitted income for non-MM2H residents have shifted since 2024, so retirees should confirm their specific visa status keeps the foreign-income exemption intact before committing.
Costa Rica: simplicity without the flat-rate paperwork
Costa Rica takes a more straightforward approach than the flat-rate European programs. There is no special application process to unlock a preferential rate, because the country simply does not tax foreign-sourced income for residents in the first place. Panama, Greece, and Costa Rica lead the field among tax-free retirement countries, and Costa Rica’s version of that appeal comes from its territorial system applying automatically rather than through a time-limited incentive program.
This matters for long-term planning, since retirees do not need to worry about a program expiring after ten or fifteen years the way they would in Greece or Italy. Costa Rica also pairs this with a well-regarded public and private healthcare system, which tends to be a bigger factor in retirement decisions than people initially expect. The absence of a flat-rate deadline means retirees can settle in without the clock ticking on their tax benefit from day one.
What changed with Portugal, and why it matters
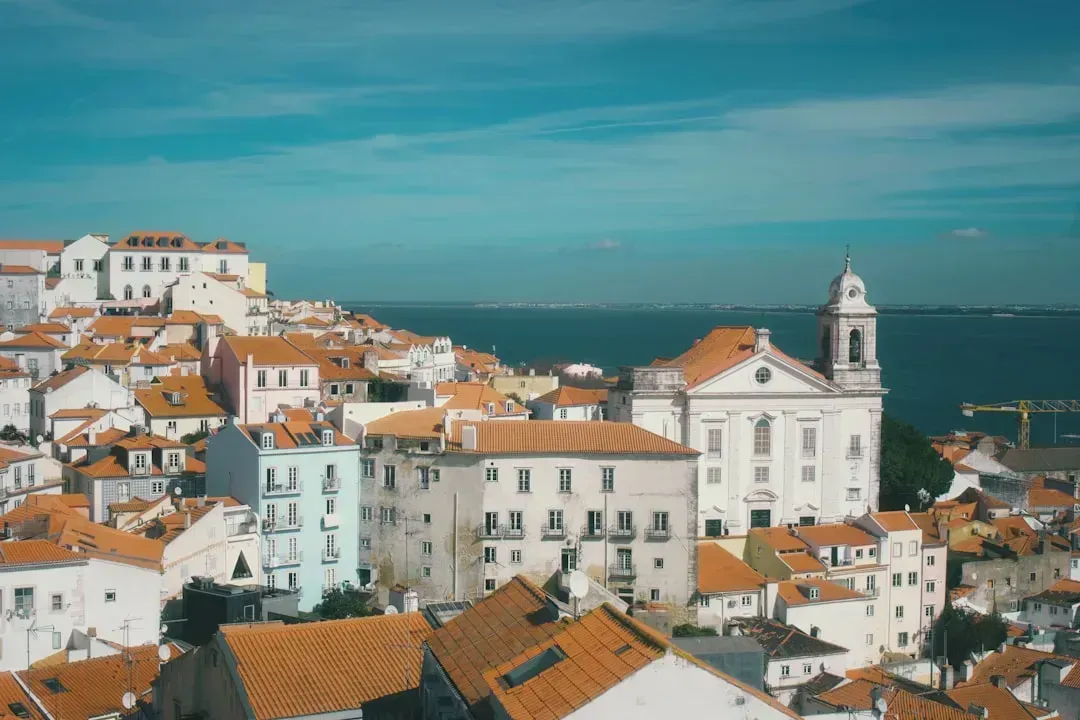
No list like this feels complete without addressing Portugal, mostly because so many retirees still assume its old tax break is available. It is not, at least not in the form that made the country famous. The original NHR program closed to new applicants on January 1, 2024, with a transitional window letting some applicants still register through March 31, 2025, provided they met specific conditions tied to 2023.
The replacement program is aimed at a completely different crowd. IFICI requires a PhD or Master’s plus five years of experience in scientific research or innovation, and excludes retirees and most digital nomads. Retirees who already secured the old NHR status before the cutoff keep their benefits for the full ten years, but anyone planning a fresh move to Portugal purely for tax reasons in 2026 needs to look elsewhere on this list instead.
Final thoughts on choosing a tax-friendly retirement
Leave a Reply