Spending Too Freely Before the Dust Settles
The first twelve months of retirement often feel like a long exhale after decades of work, and that emotional shift tends to loosen the purse strings. Financial professionals sometimes call these the “go-go years,” a stretch when retirees naturally want to travel, renovate, or finally spend on things they postponed. Many retirees naturally spend more in early retirement, then less as they age and slow down, so building this flexibility into a plan makes it more resilient.
The trouble is that a new retiree rarely has a real sense of what their monthly expenses will actually look like without a paycheck. Housing, healthcare, and discretionary costs all shift at once, and without tracking them closely, it’s easy to overshoot a sustainable number before realizing it. Setting a budget requires knowing precisely how much money is coming in, tracing all sources of cash including Social Security, pension, work income and investments, then categorizing expenses like housing, utilities, groceries, healthcare and discretionary spending.
Walking Into a Bad Market at the Wrong Moment
Timing isn’t something anyone controls, but it shapes retirement outcomes more than most people realize. Sequence of returns risk is the danger that poor investment returns early in retirement, combined with ongoing withdrawals, will significantly reduce a portfolio’s value and limit its ability to recover. Two people can retire with identical savings and nearly identical investment strategies, yet end up in very different financial positions a decade later simply because of when the good and bad years happened to fall.
Research by Wade Pfau estimates that approximately 77% of a portfolio’s final retirement outcome can be explained by the returns of just the first 10 years. That statistic alone should give anyone pause before assuming average long-term market returns will smooth everything out. This matters because it can jeopardize long-term financial security, especially in the first decade of retirement, when portfolio balances are largest and most vulnerable to market downturns.
Selling Investments at Exactly the Wrong Time
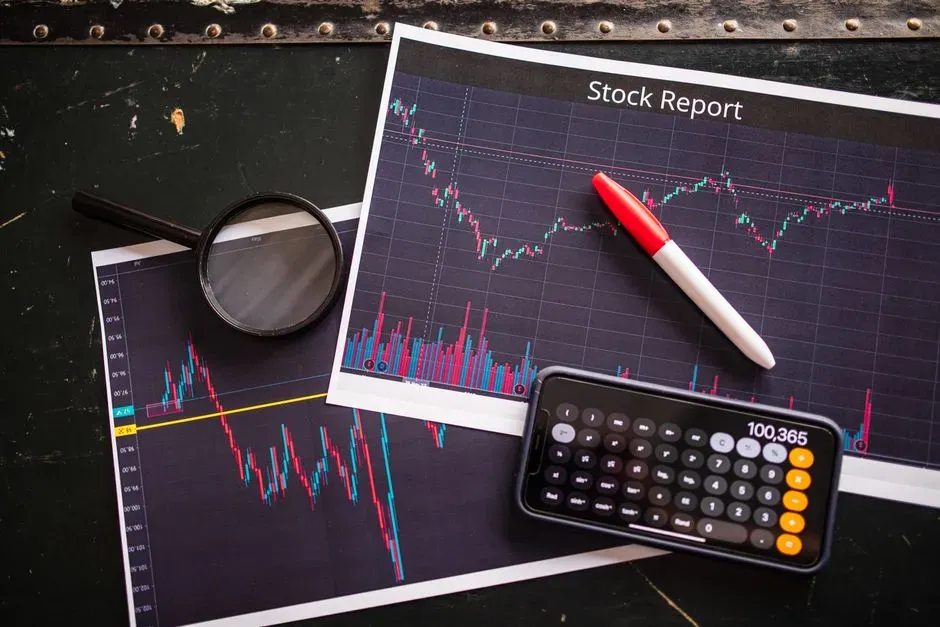
When markets dip early in retirement, the instinct to keep withdrawals steady can quietly do lasting damage. When markets fall in the early years of retirement, retirees are forced to sell more shares to fund the same withdrawal at exactly the wrong time, and those shares are gone forever and can’t participate in the eventual recovery. It’s a subtle mechanism, easy to miss in the moment, but it compounds year after year.
This is different from the market risk everyone worries about during their working years. During working years the order of returns doesn’t matter much, since a loss followed by a gain produces a similar result as the reverse when no money is being pulled out, but once withdrawals begin, early losses compound in a way that later gains can’t undo. That distinction is exactly why the first year of retirement carries so much weight.
Skipping the Cash Buffer Entirely
One of the more practical defenses against a rocky start is also one of the most overlooked: keeping a chunk of savings in something that isn’t tied to the stock market’s daily mood swings. A common way to guard against this risk is a bucketing strategy, holding a few years’ worth of living expenses in safe, liquid assets like cash and bonds so that money can be drawn from that safe bucket during a downturn instead of selling long-term growth investments at a loss. Retirees who skip this step often find themselves forced into selling stocks precisely when prices are down.
Some advisors extend this idea into a three-tiered structure. One version divides savings into three buckets, the first kept in liquid assets covering income needs for the first three to five years, the second invested more aggressively for growth over the following decade, with money periodically shifted into liquid assets as it’s needed. Setting this up before retirement begins, rather than scrambling afterward, makes a real difference.
Underestimating Healthcare Costs Before Medicare Kicks In
Anyone retiring before 65 faces a gap that catches many people off guard. Individuals aren’t eligible for Medicare coverage until age 65, so bridging healthcare coverage in the intervening years has the potential to increase spending. That bridge isn’t cheap, and it eats into savings faster than most early retirees anticipate.
The numbers make the point clearly. Insurance coverage for 62 to 65 year olds from the ACA marketplace averaged between $800 and $1,200 a month in 2025, while COBRA coverage for the same age group averaged $700 to $1,500 a month. For someone drawing a modest, supposedly safe withdrawal rate, healthcare costs alone could consume roughly a third of those withdrawals for a 62-year-old taking a 3.5% withdrawal from a $1 million portfolio.
Sticking Rigidly to a Withdrawal Number That No Longer Fits
Many new retirees pick a withdrawal percentage before retiring and then treat it as gospel, refusing to adjust even when circumstances change. That rigidity can be a costly habit, especially if the first few years bring market losses. A rebounding market should help retirees quickly make up lost ground, but continuing withdrawals can create a strong headwind, with more shares sold to support spending in a down market than would be the case when values are appreciating.
A more flexible approach tends to hold up better under pressure. If markets struggle in the early retirement years, reducing spending temporarily or working part-time can help protect the portfolio. It’s not a comfortable adjustment to make emotionally, but the retirees who build in that flexibility from day one tend to weather rough patches with far less damage to their long-term security.
Leaving Old Retirement Accounts Behind
It’s easy to assume that once savings are tucked into a 401(k) or similar account, the job is basically done. Yet plenty of people change jobs multiple times over a career and simply lose track of what they left behind. According to a 2025 report by Capitalize, Americans have left behind or forgotten 32 million accounts totaling $2.1 trillion in assets.
Forgotten accounts can’t be managed, rebalanced, or factored into a coherent retirement income plan. Someone entering their first year of retirement without a full accounting of every account they own is essentially guessing at their own financial picture. Consolidating or rolling over old employer plans before retirement begins removes a layer of unnecessary uncertainty right when clarity matters most.
Ignoring the Interest on Everyday Debt
Carrying credit card debt into retirement is more common than most people assume, and it quietly undermines even a well-funded plan. More than half of Gen Xers and over two in five boomers carry a credit card balance from month to month. With the average credit card rate reaching nearly 24 percent in December 2025, that balance grows fast on a fixed income.
The danger isn’t always dramatic overspending. The biggest financial trap that older Americans typically fall into is using credit cards as supplemental income, treating a card balance as a stopgap rather than confronting a budget shortfall directly. Left unchecked through the first year, that habit can undo years of careful saving.
Overlooking the Possibility of an Unplanned Long-Term Care Bill
Most retirement projections assume a fairly linear path, but real life rarely cooperates that neatly. Spending shocks can also curb a retirement portfolio’s longevity, and researchers have examined two major types, unanticipated early retirement and uninsured long-term care expenses at the end of life. Neither shows up in a simple spreadsheet projection, yet both can upend an otherwise solid plan.
Long-term care costs in particular can translate into an effective balloon payment toward the end of life, arriving all at once rather than spreading out gradually. Retirees who ignore this possibility in year one, assuming it’s a problem for “future them” to solve, often find there’s less flexibility left to absorb the shock by the time it actually arrives.
Treating the Plan as Finished Instead of Living
Perhaps the quietest first-year mistake is assuming that once retirement begins, the planning work is over. A retirement income strategy needs regular updates, since market performance, tax law changes, and personal circumstances all require adjustments, and reviewing the plan annually at minimum is generally recommended. Life doesn’t pause just because someone has stopped working.
Inheritances, new health diagnoses, a desire to relocate, all of these can shift the math significantly. Events like inheriting money, developing health issues, or wanting to move all trigger the need for plan revisions. Retirees who check in on their numbers every year, rather than setting the plan on autopilot, catch small problems before they become permanent ones.
What This Adds Up To
None of these mistakes look dramatic in isolation. A slightly higher withdrawal, a market dip absorbed by selling stocks instead of cash, a forgotten 401(k), a credit card balance carried one month too long. Individually, each one seems survivable.
Stacked together in a single first year, though, they can quietly set the tone for everything that follows. The retirees who fare best tend to be the ones who treat that first year not as a finish line, but as the most consequential twelve months of the entire retirement.

Leave a Reply