There’s a popular image of the millionaire life: luxury cars in the driveway, business class flights, and dinner reservations at places with no prices on the menu. The reality, for a large share of genuinely wealthy people, looks quite different. Research dating back to Thomas Stanley and William Danko’s classic work “The Millionaire Next Door” revealed that most millionaires lived in middle-class neighborhoods, drove modest cars, and avoided ostentatious displays of wealth. That finding hasn’t aged out of relevance.
Accountant and financial planner Tom Corley, who studied wealthy people’s habits for five years, determined that most of their wealth was built by strict frugality and only spending on the absolute necessities, cutting back on the ordinary spending habits many of us don’t even realize we’re engaging in. The list below covers twelve categories where frugal millionaires routinely say no, even when they could easily say yes.
1. Brand-New Cars with Steep Depreciation
A brand-new car loses at least ten percent of its value in the first month of ownership, and after one year it will be worth about twenty percent less than what was paid for it. That’s a staggering loss for something sitting in a parking lot. After five years, that new car has lost around sixty percent of its value.
You’d think millionaires would be first in line for the latest luxury car, but plenty of them just don’t see the point. A brand-new car loses value the second it leaves the lot, and depreciation doesn’t slow down. That’s why so many financially savvy millionaires skip the high-end brands and stick with reliable, fuel-efficient cars instead. Some, like entrepreneur Shang Saavedra, share a seventeen-year-old secondhand vehicle despite having a multi-million-dollar net worth.
2. Extended Warranties
Extended warranties are pushed hard at the checkout counter because they’re pure profit for the store. The math rarely works out in the buyer’s favor, and you’re almost always better off putting the cost of the warranty into a savings account and self-insuring against broken electronics or appliances. It’s one of the retail industry’s most reliable upsells for good reason.
Warranties are rarely used, and if you’re buying reliable, high-quality products, your regular manufacturer’s warranty should suffice. Getting the extended warranty might not even equal greater service if you do need it; it may take longer to get fixed. Wealthy individuals often have broader insurance policies in place to cover personal property at more favorable rates, making individual item warranties redundant.
3. Luxury Brand Clothing
Many frugal millionaires don’t need a designer logo to prove they can afford expensive clothes. True wealth is quiet. Quality, durability, and fit matter far more than flashy brands that charge a steep markup just for a label. The wardrobe philosophy here is fundamentally practical.
Self-made millionaire Jonathan Sanchez keeps a small closet of simple, timeless clothes, not overthinking outfits. Blue jeans and a T-shirt for casual settings, a suit and tie for formal events. This approach lets him avoid the temptation of spending on flashy new outfits or cheap, disposable fashions. Fast fashion, in particular, is seen as costly and wasteful.
4. Daily Coffee Shop Habits
A five-dollar coffee doesn’t sound like much until you add it up. That’s roughly eighteen hundred dollars a year, gone. Smart millionaires don’t waste money on a daily latte habit when brewing at home costs a fraction of the price. A high-quality coffee maker and good beans give the same result without the retail markup.
This isn’t about deprivation. It’s about recognizing where money quietly disappears. The coffee shop line is one of the more visible examples of a pattern that applies to dozens of daily micro-purchases. Being intentional about money ensures that every dollar is spent on something that adds real value to your life.
5. Timeshares
Timeshares are notorious money pits. You pay a massive upfront cost, plus ever-increasing annual maintenance fees, for a property you don’t actually own and will likely struggle to sell later. The secondary market for timeshares is notoriously illiquid, which compounds the problem significantly.
Frugal millionaires tend to prefer flexibility in their travel. Instead of high-end hotels or locked-in travel arrangements, they opt for well-reviewed rentals or boutique stays that offer better value. The trip is the experience, not the room. Paying ongoing fees for a fixed week at a single resort is almost the opposite of that mindset.
6. Redundant Subscriptions
Accumulating subscriptions just because each one is “only ten dollars a month” adds up fast. These little monthly expenses might not cause bankruptcy, but maintaining a mindset of avoiding waste matters. They call it lifestyle creep because it has a way of sneaking up on you. Being vigilant, even about small things, helps ensure every dollar is still being spent with intention.
In the digital age, it’s easy to accumulate multiple subscription services that quickly add up. Taking a critical look at current subscriptions, including streaming platforms, gym memberships, and magazine subscriptions, and identifying unused or redundant services helps free up funds. Most people are surprised by what they find when they actually audit the list.
7. Lottery Tickets and Gambling
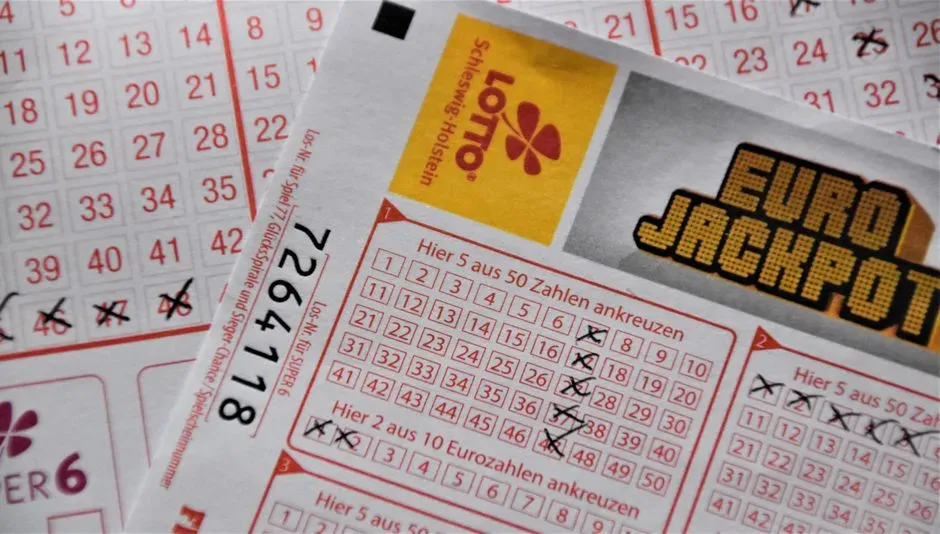
Lottery tickets are widely seen by wealth-builders as a voluntary tax on people who underestimate the odds. The chances of winning a big jackpot are practically zero, and you’re far better off taking that five or ten dollars a week and putting it into a low-cost index fund. The math is simply not debatable.
A 2024 study by the University of California San Diego found that roughly ninety-six percent of more than 700,000 gamblers lost money. Only about four percent made money from online betting, and that outcome is by design, with platforms known to throttle or ban frequent winners. Frugal millionaires see gambling for what it is: a transfer of wealth in the wrong direction.
8. Name-Brand Groceries When Generics Are Identical
If there are no complaints about the generic ibuprofen or store-brand pasta, there’s no reason to pay more for name brands just because the money is available. The extra dollar here and there might not derail finances, but that’s money that could be parked in high-yield savings accounts or investment portfolios – or spent on things actually worth the premium.
Whether it’s soda brands or athletic apparel, one of the common things frugal people refuse to buy regardless of income level is name-brand products with unnecessary price premiums. Most brands increase prices precisely because customers will pay whatever it takes. Frugal millionaires simply opt out of that dynamic.
9. Eating Out as a Daily Default
While not cooking dinner is enjoyable, it works best as an occasional indulgence rather than a daily habit. Eating out or ordering takeaway can quickly erode a budget, while cooking meals at home saves money and provides better control over nutrition and portion sizes. This is one of the most straightforward costs to control.
Middle-class households tend to overspend on dining out partly because people overstock their fridges with food they’re too tired or unmotivated to cook, then go out to eat instead, effectively doubling their food expenses. Being more intentional about eating out and actually planning for it in a budget makes a measurable difference. Even Warren Buffett has noted that he prefers eating at home because it’s simply much less expensive.
10. Unnecessary Gadget Upgrades
Upgrading a phone every year when you wouldn’t have done so before gaining wealth is still wasteful and mostly unnecessary. If you’re still doing fine with the tech you have, that upgrade money is better spent on something that would bring genuine joy. The same principle applies to laptops, tablets, and smartwatches.
Wealthy individuals avoid paying extra for something that becomes worth less every year. If it loses value over time, they prefer to own it outright or skip it entirely. The cycle of trading in last year’s phone for this year’s model is, from a wealth-building perspective, closer to a treadmill than a ladder.
11. Bank Fees and Overdraft Charges
Never paying bank fees is one of the easiest and most avoidable ways to stop wasting money. The average overdraft fee runs around thirty-five dollars, and roughly eleven percent of Americans paid one in 2024. Frugal millionaires tend to treat fee avoidance as a baseline habit, not an optional nicety.
Overdraft fees or charges for not maintaining a minimum balance can add up quickly. Moving to a bank that offers fee-free accounts is a straightforward solution. The same discipline applies to insurance: avoiding double coverage that provides the same protection, streamlining plans to ensure the right protection without redundant policies, and freeing up cash to reinvest elsewhere.
12. Lifestyle Inflation After an Income Increase
When income rises, most people upgrade everything: bigger house, better car, more spending. Wealthy people largely don’t. They keep their lifestyle stable and let savings grow instead. This single habit – resisting lifestyle upgrades – is often what separates long-term wealth from lifelong financial pressure.
Because you don’t have to be frugal out of necessity doesn’t mean you shouldn’t care about wasteful spending. By maintaining frugal habits when you don’t technically need to, you can ensure that the wealth you’ve built is going toward the things you care about, and that lifestyle creep won’t wipe out your assets faster than anticipated. That last point is harder than it sounds in practice, which is probably why it matters so much.
The common thread running through all twelve of these categories isn’t deprivation. It’s the deliberate refusal to let money drift toward things that provide almost no lasting value. Becoming a millionaire is mostly about what you don’t buy. Wealth built over time tends to come from consistent investing, hard work, and ruthlessly cutting out purchases that simply don’t make mathematical sense. The habits above aren’t sacrifices for most frugal millionaires. They’re just the way money works when you pay close attention to it.

Leave a Reply