Ask ten people where they plan to retire and you will likely get ten different answers built around sunshine, mountains, or proximity to grandkids. Yet when you ask financial researchers where a retirement nest egg actually stretches the farthest, the answers cluster in a surprisingly consistent part of the map. Lower housing costs, modest utility bills, and friendlier tax codes tend to matter more than palm trees when it comes to making savings last for decades rather than years.
Several recent 2026 cost-of-living and retirement-readiness studies, including analyses from GOBankingRates, WalletHub, and Retirement Living, point to a familiar group of states where a fixed income goes noticeably further. Below are nine states that consistently show up near the top of these rankings, along with the specific reasons retirees find their money stretching longer there.
West Virginia
West Virginia routinely tops affordability lists for retirees, and the numbers back up the reputation. With an annual cost of living after Social Security of $27,803, a $1.5 million nest egg would last about 54 years, the longest of any state. That figure reflects some of the lowest housing and utility costs in the country.
The tax picture has also improved recently. West Virginia ranked first for affordability in both Bankrate’s 2025 study and Retirement Living’s 2026 study, and no longer taxes Social Security. For retirees relying heavily on benefit checks, that change alone can meaningfully extend how long savings hold up.
Kansas
Kansas rarely gets the attention that Sun Belt states do, but its cost structure quietly favors retirees. The annual cost of living after Social Security is $28,945, which means $1.5 million would last approximately 52 years. That places it just behind West Virginia in raw longevity of savings.
Beyond the raw numbers, housing plays a big role. Kansas can be an appealing choice for retirees seeking predictable, relatively moderate everyday expenses, with housing remaining affordable across much of the state, particularly outside the Kansas City suburbs. Smaller communities scattered across the state tend to offer the biggest savings on housing without sacrificing access to basic services.
Mississippi
Mississippi shows up on nearly every affordability list, and for good reason. Retirees can expect their savings to last about 51 years, thanks to a modest annual cost of living of $29,426 after Social Security. That kind of longevity is difficult to match in most other regions of the country.
Tax policy adds another layer of appeal. The state also offers tax-friendly policies for retirees, including exemptions on Social Security income. Combined with housing costs well below the national average, Mississippi consistently ranks as one of the most budget-friendly places to spend retirement years.
Oklahoma
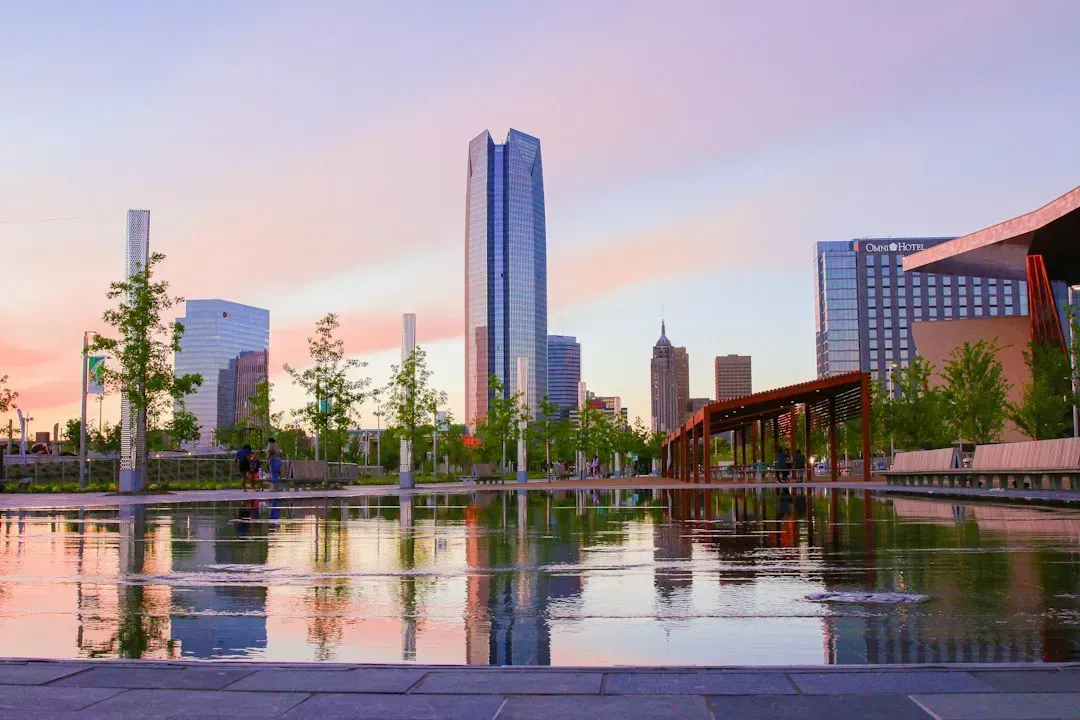
Oklahoma has become something of a poster child for retirement affordability in recent years. With an annual cost of living of $29,666 after Social Security, $1.5 million would last roughly 51 years. Separate GOBankingRates research using a different methodology reaches a similar conclusion about the state’s staying power.
That research found that Oklahoma, Mississippi and Alabama ranked as the top three states where $1 million affords 18+ years in retirement. The consistency across multiple independent studies suggests the affordability advantage is not a statistical fluke but a genuine reflection of low housing and grocery costs statewide.
Alabama
Alabama rounds out the trio of Southern states that dominate national affordability rankings. Retirees in Alabama would see their savings last about 50 years due to an annual post-Social Security cost of living of $30,207. That places it within a few years of Oklahoma and Mississippi in terms of pure savings longevity.
WalletHub’s broader retirement research reinforces the state’s standing among low-cost options nationally. Its 2026 rankings placed Alabama among the top affordability performers, tied closely with West Virginia in several affordability-related categories. For retirees prioritizing warmer weather without sacrificing budget, Alabama offers a rare combination of both.
Iowa
Iowa does not always make headline lists, but its combination of affordable housing and improving tax treatment has moved it up in recent rankings. Iowa’s relatively affordable housing and strong network of smaller communities can help retirement savings stretch further, and the state also eliminated its tax on qualifying retirement income for eligible residents. That tax change is relatively recent and has meaningfully boosted the state’s appeal for retirees living on pensions or retirement account withdrawals.
Retirement Living’s 2026 analysis has actually named Iowa its overall winner in one influential ranking, according to research summarized by Annuity.com. The state’s steady, unglamorous approach to affordability, small towns, modest home prices, low crime, tends to appeal to retirees who prioritize predictability over flash.
Missouri
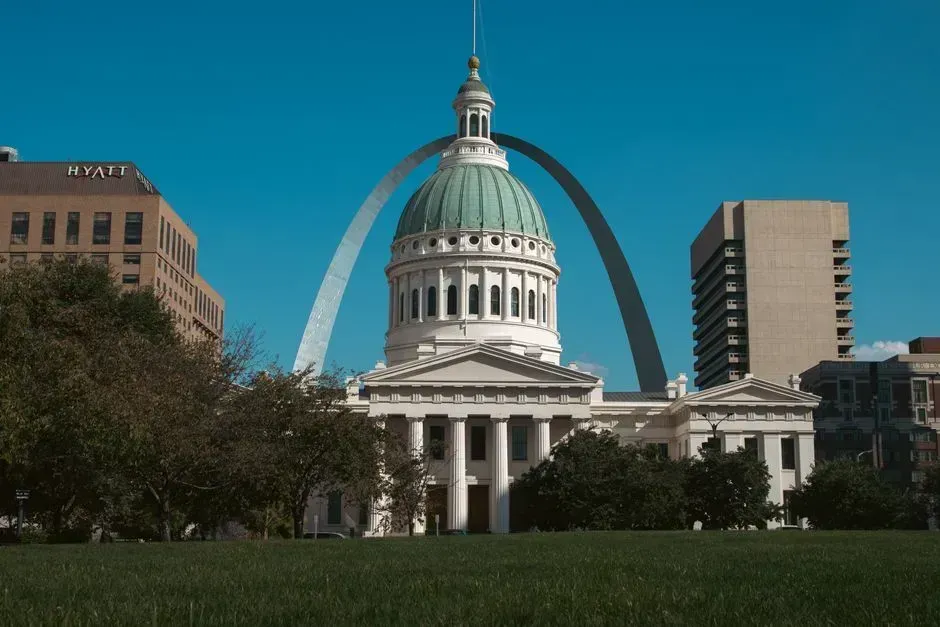
Missouri offers something a bit different from the smaller, more rural states on this list: affordability without total isolation from urban amenities. Missouri gives retirees several affordable options without requiring them to live far from major services, with smaller cities and towns generally offering modest housing costs while areas surrounding St. Louis, Kansas City, Springfield, and Columbia provide access to healthcare and cultural amenities at costs that are often lower than comparable metropolitan areas elsewhere.
That balance matters more than people expect once retirement actually begins. Many retirees discover they want occasional access to specialists, airports, and cultural events even if they plan to spend most of their time in a quieter setting. Missouri’s mix of affordable smaller cities near larger metro areas gives retirees that flexibility without the price tag that usually comes with it.
Arkansas
Arkansas consistently appears alongside Mississippi and West Virginia in cost-of-living comparisons, and Empower’s 2026 retirement research grouped it among the states with the lowest overall expenses. States like Mississippi, West Virginia, and Arkansas consistently rank among the lowest in cost of living, with lower housing, healthcare, and daily expenses. That combination of low housing and low healthcare costs is particularly valuable for retirees, since medical spending tends to rise steadily with age.
Arkansas also benefits from a relatively low overall tax burden compared to many neighboring states, though its income tax structure is more moderate than the fully tax-free states further west. For retirees who have already downsized and are focused primarily on stretching a fixed monthly income, the state’s day-to-day affordability tends to outweigh the tax nuances.
Wyoming
Wyoming takes a different route to affordability than the Southern and Midwestern states on this list, relying heavily on the absence of state income tax rather than simply low prices. WalletHub cited Wyoming’s retiree appeal as driven largely by affordability, with a retiree-adjusted cost of living in the more affordable half of the nation, a retired taxpayer-friendly environment that includes no estate or inheritance tax, and the fifth-lowest annual cost of homemaker services. That last detail matters more than it might seem, since in-home care costs can quietly consume a large share of retirement savings as people age.
Wyoming’s broader quality-of-life numbers also support its ranking. The state’s overall quality-of-life factors included the 10th-best elder-abuse protections, the fifth-lowest violent crime rate and the 14th-highest share of residents who do favors for their neighbors, while financially the state had the seventh-lowest share of residents 65 and over in poverty. For retirees drawn to open space and low taxes rather than warm winters, Wyoming offers a version of affordability built on policy rather than climate.
How these rankings are calculated
It is worth understanding how researchers actually arrive at these numbers, since methodology varies between studies. GOBankingRates found the national average annual expenditures for people ages 65 and older in every state, then created state-level annual expenditure estimates by multiplying the national figure by each state’s overall cost-of-living index score, with the number of years $1 million lasts in each state determined by dividing $1 million by each state’s average annual expenditures estimate. Other analyses, like the one behind the West Virginia and Kansas figures cited above, factor in Social Security income before calculating how long remaining savings will last each year.
These differences in methodology explain why the exact number of years attached to a given state can shift slightly from one study to the next, even when the same states keep appearing near the top. What stays consistent across nearly every major 2026 analysis, whether from GOBankingRates, WalletHub, Retirement Living, or MoneyLion, is the general geography: lower-cost states concentrated in the South and parts of the Midwest tend to make retirement savings last dramatically longer than high-cost states like Hawaii, California, or Massachusetts, where the same $1.5 million might only last 17 years in Hawaii, the shortest of any state.

Leave a Reply