1. They drive their cars into the ground
The stereotype says wealthy people roll up in something German and expensive. The data says otherwise. A study of 10,000 U.S. millionaires found that most of them avoided driving expensive luxury brands, with nearly one-third of all millionaires driving Toyotas and Hondas. Ford came in third, tied with Lexus, and both landed at a modest single-digit share.
Separate survey data backs this up from a different angle. When you think “millionaire,” you probably don’t imagine someone driving an older, high-mileage car, but a millionaire survey found that most clients tend to drive cars for over seven years. Driving vehicles for as long as reasonably possible makes sense because cars are depreciating assets, but depreciate the most in the first three to five years. It’s not that they can’t afford a new car. It’s that they’ve done the math and decided against it.
2. They live on less than they earn, deliberately
This one sounds obvious, yet it’s the habit most people skip. Even when millionaires don’t have to worry about money anymore, they’re still careful about their spending, with ninety-four percent of the people studied saying they live on less than they make. That gap between income and spending is where wealth actually gets built, not in the income figure itself.
It also shows up in how they handle short-term debt. Nearly three-quarters of the millionaires studied have never carried a credit card balance in their lives. That’s not a coincidence. Living below your means and staying out of revolving debt tend to travel together, and neither one requires a high salary to pull off.
3. They rarely rely on one lucky break
The “young genius sells an app overnight” story is compelling, but it’s not how most wealth gets made. Three out of four millionaires said that regular, consistent investing over a long period of time is the reason for their success, and the story about the young computer genius who developed an app that earned millions overnight is the exception, not the rule. The slow version just doesn’t trend on social media.
This shows up again in more recent data. Many of the Americans who crossed the seven-figure threshold in 2025 likely didn’t become millionaires because of one extraordinary investment, but through years of consistently investing in retirement accounts and diversified portfolios, boosted by another strong year for financial markets. Consistency, applied for decades, tends to beat timing the market.
4. They max out the boring retirement account first
Before angel investing or real estate syndicates, most wealthy people start somewhere unglamorous: the workplace retirement plan. The National Study of Millionaires found that 8 out of 10 millionaires listed investing in their employer-sponsored plan as a primary vehicle for reaching millionaire status. It’s automatic, it’s tax-advantaged, and it doesn’t require picking winning stocks.
What’s notable is how little flash is involved. There’s no hot tip, no insider access, just payroll deductions compounding quietly for twenty or thirty years. It’s the financial equivalent of watching paint dry, except the paint eventually turns into a comfortable retirement.
5. They treat reading as a competitive advantage
This habit gets mentioned a lot, but it’s worth taking seriously rather than treating as a throwaway line. One of the reasons millionaires become millionaires is because of their constant desire to learn, and to them, leadership books and biographies are much more important than the latest reality show or trend. It’s less about status and more about staying current on decisions that matter.
Time-use research backs this up with harder numbers. One study shows that 88% of millionaires dedicate at least 30 minutes daily to self-education, reading books on personal development or industry trends, while a majority of lower-income individuals in the same study spent over an hour a day on screen-based entertainment instead. The gap isn’t dramatic day to day, but it compounds over years the same way money does.
6. They avoid inheritance as a plan
There’s a persistent myth that most wealth is inherited. The research says the opposite. The research found 79% of millionaires didn’t receive an inheritance at all. A separate figure from a different source lands in a similar range for the ultra-wealthy.
Approximately 60% of those with net worths of at least $30 million are “self-made,” meaning they earned their money through entrepreneurship, investments, or their own salaries instead of inheriting it. That doesn’t mean luck and family circumstance play no role. It just means most of the actual dollar accumulation happens through decades of earning and investing, not a single family windfall.
7. They don’t chase prestige degrees
The assumption that wealth requires an Ivy League pedigree doesn’t hold up well against the data. Almost two-thirds of millionaires, 62%, graduated from public state schools, while only 8% went to a prestigious private school. The degree mattered more than the institution’s name on it.
This one quietly undercuts a lot of anxiety around college admissions. It suggests that what you do with an education, the discipline and follow-through afterward, counts for more than the brand printed on the diploma. Wealthy families rarely bring this up, maybe because it’s less impressive to say “state school” than “Ivy.”
8. They keep an emergency fund and save aggressively
Wealthy people don’t just invest, they also hoard cash reserves in a way that looks almost overly cautious. A huge part of building wealth is limiting your lifestyle so there’s actually money to invest and save for a rainy day, and nearly half the millionaires studied in The National Study of Millionaires said they save at least 16% of their monthly income. That’s a meaningfully higher savings rate than most household budgets allow for.
This habit rarely gets discussed because it sounds unsexy compared to investment returns. Still, an emergency fund is what keeps a bad year from turning into a bad decade. It’s insurance against having to sell investments at the worst possible time.
9. They keep credit cards, but use them strategically
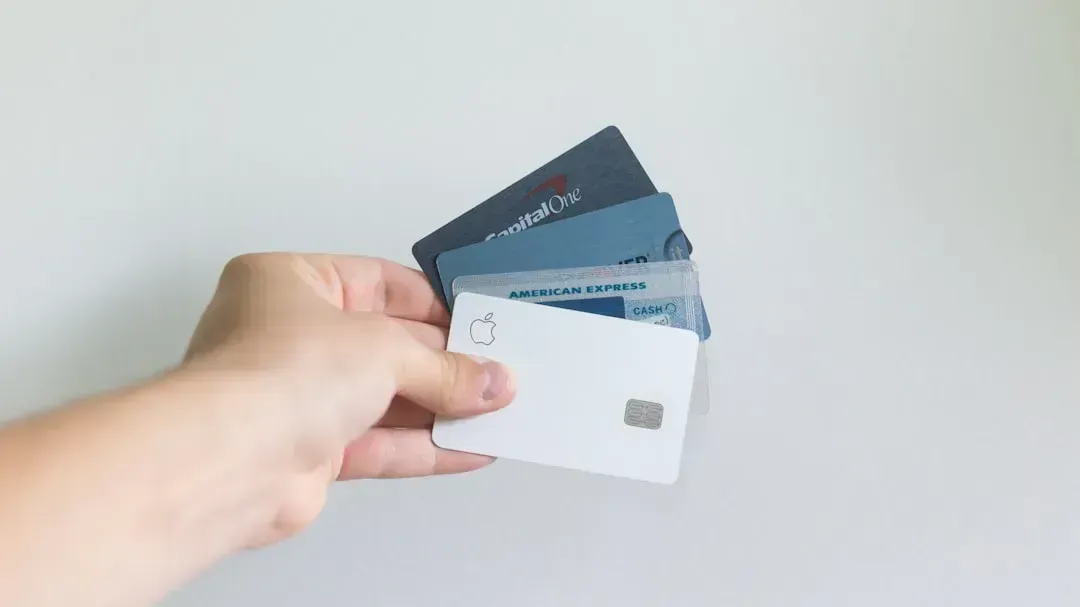
Contrary to the assumption that the wealthy avoid credit entirely, they actually use it more, just differently. Millionaires are more than twice as likely to have a travel credit card as non-millionaires, and most millionaires have two or more credit cards, compared to a much smaller share of those with a net worth under one million dollars. The cards aren’t the point. The point is what they extract from them, in rewards, protections, and float, without ever paying interest on a balance.
This distinction matters more than it seems. Credit itself isn’t the enemy; unpaid balances are. Wealthy households tend to treat cards as a tool for convenience and rewards rather than a way to stretch a budget that doesn’t otherwise work.
10. They set specific, written goals instead of vague intentions
“I want to be rich” and “I want to save $500,000 for a house down payment by 2029” are not the same kind of goal, and wealthy people tend to favor the second type. In one Rich Habits study, 80% of self-made millionaires set specific, long-term goals and focused on them daily, defining a clear vision and breaking it into daily tasks. Vague ambition rarely survives contact with a busy week; specific numbers do.
This ties into a broader planning habit that shows up in newer research too. Seventy-six percent of American millionaires consider themselves to be disciplined financial planners, compared to forty-nine percent of the general public, according to Northwestern Mutual’s 2025 Planning and Progress Study. The gap isn’t enormous, but it’s consistent, and consistency is the whole game here.
11. They know their retirement number, not just a vague hope
Ask most people how much they’ll need to retire comfortably and you’ll get a shrug. Ask a millionaire and you’ll often get a specific figure. Wealthy Americans don’t just save for retirement, they know how much they need to save, with 77% of American millionaires knowing how much money they will need to retire comfortably compared to 45% of the general public. That clarity changes behavior long before retirement actually arrives.
Knowing the number turns retirement from an abstract worry into a math problem with a deadline. It’s easier to save consistently toward a target you can picture than toward a fuzzy sense that “more is better.” This is one of those habits that costs nothing to copy, just an afternoon with a calculator.
12. They give away more than people assume
Generosity doesn’t fit the stereotype of hoarded wealth, but the numbers tell a different story at the top end. According to IRS data, in 2022, individuals with adjusted gross income over $10 million donated $55.9 billion, accounting for 48.2% of all donations. That’s a striking share coming from a very small slice of taxpayers.
This habit rarely comes up in casual conversation, partly because discussing your own charitable giving can feel like bragging. Still, it’s a consistent pattern across wealth research: once basic security is achieved, giving becomes part of the financial routine rather than an afterthought. It’s one more way that quiet wealth differs from its loud, performative cousin.
None of these habits are secret in the sense of being hidden information. They’re just unremarkable enough that nobody brings them up at parties. Driving an old Honda, reading before bed, checking a retirement calculator, none of it makes for a good story. But taken together, over twenty or thirty years, these small and slightly dull choices are what actually separate a comfortable retirement from a stressful one.

Leave a Reply